Retailer Reach Among German Online DIY Shoppers
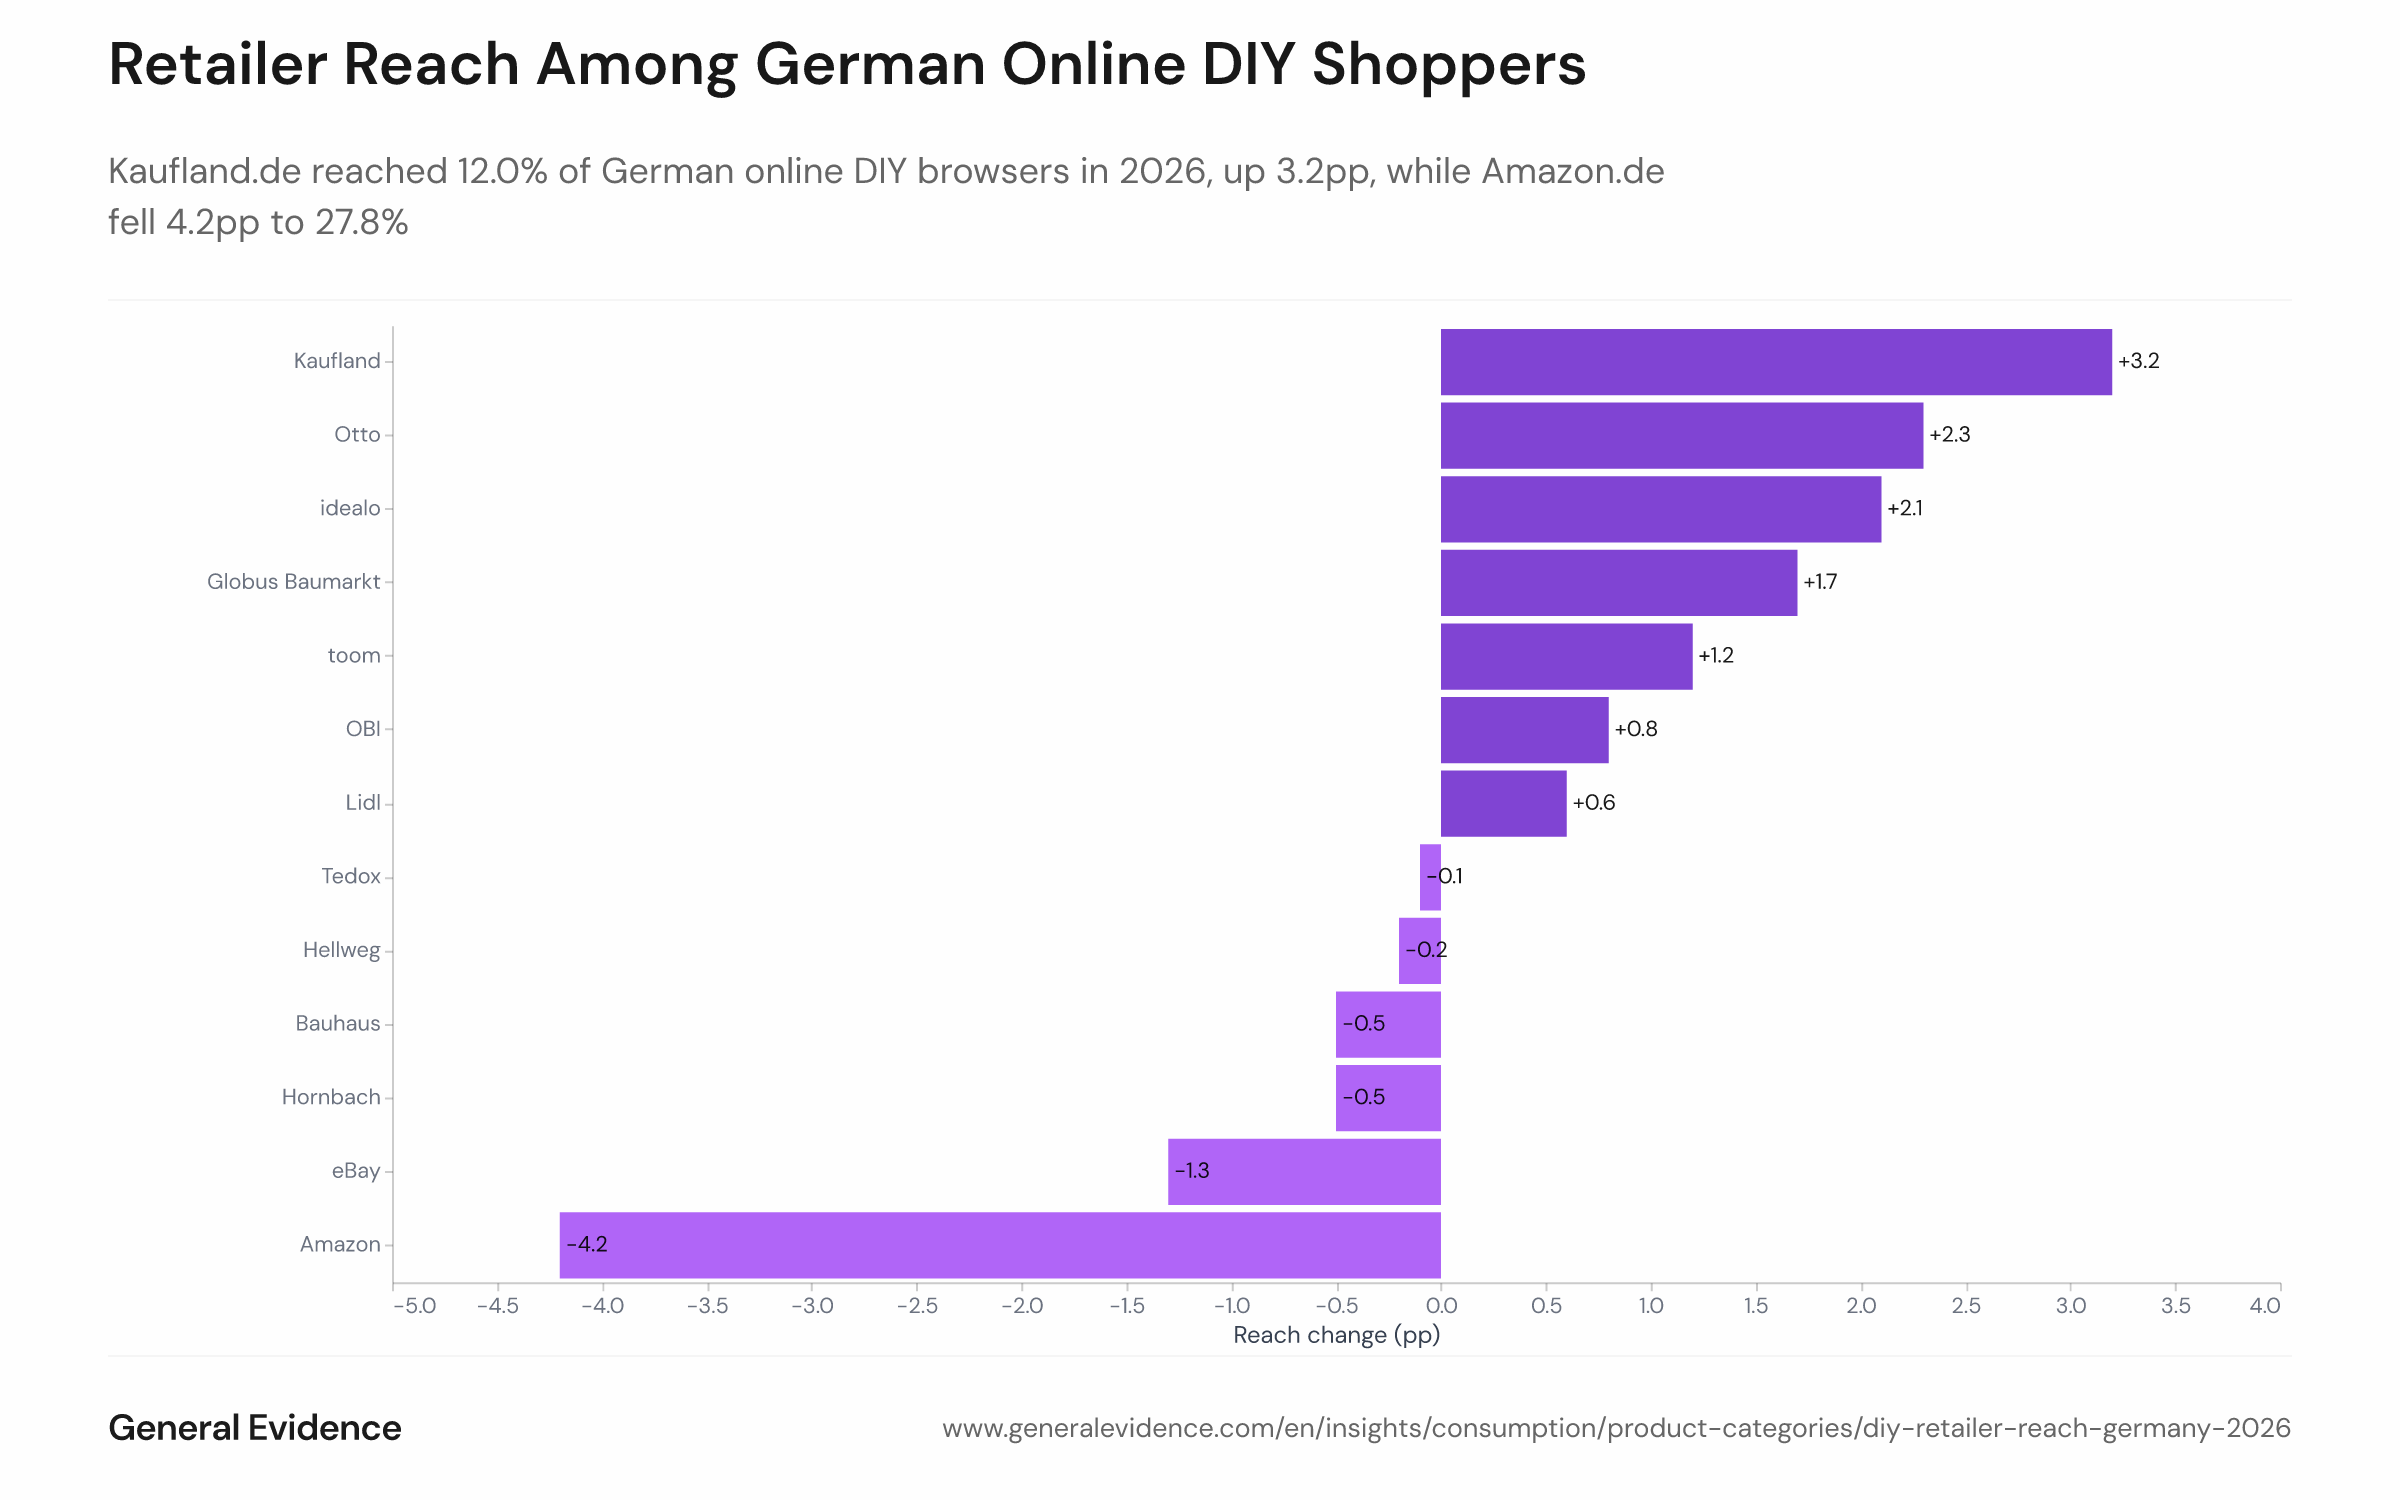
Review Jan–Sep 2025 vs. Jan–Sep 2026: Kaufland.de reached 12.0% of German online DIY browsers in 2026, up 3.2pp, while Amazon.de fell 4.2pp to 27.8%
License: CC BY 4.0 · Source: General Evidence · How to reuse
Info
- Sample size
- n = 16,030
- Data date
- Jan–Sep 2025 vs. Jan–Sep 2026
- Segment
- All segments
- Platform
- Browsing
- Market
- Germany
Analysis
Among Germans browsing DIY and renovation product pages online, Kaufland.de's reach jumped from 8.8% to 12.0% (+3.2pp) between the first nine months of 2025 and the same period in 2026 — the largest gain among all measured retailers. Otto (+2.3pp to 11.5%) and price-comparison platform Idealo (+2.1pp to 13.0%) also made notable advances, pointing to a broader shift toward general e-commerce destinations and price-discovery tools for home improvement purchases.
Amazon loses ground as marketplace competition intensifies
Amazon.de remained the single most-reached retailer among DIY browsers at 27.8%, but its reach fell by 4.2 percentage points — by far the largest loss in the ranking. The established specialist chains — OBI (19.3%), Bauhaus (14.2%), and Hornbach (12.8%) — held broadly steady, suggesting the share shift is flowing primarily from Amazon to general-purpose platforms rather than back toward dedicated DIY retailers. Hellweg and Tedox, both facing store-closure programmes in 2025–2026, showed flat online browsing reach (1.2% and 2.2% respectively), confirming that their physical retrenchment did not translate into a meaningful online audience gain. Germany's online DIY penetration remains below the European average despite heavy marketplace investment by OBI, Bauhaus, and Hornbach; the Kaufland and Otto gains suggest that shoppers are increasingly price-shopping renovation items across supermarket-style platforms. For the overall trend in DIY buyer penetration, see Online DIY Shopping Penetration in Germany.
This analysis is based on public segment data. For deeper cuts, use our Enterprise interface.
Ask your own question of this data.
This chart is one cut of the panel. In a demo we answer your question on the same data, live.
Methodology
Retailer reach measures the share of active German adults who viewed at least one DIY or renovation product page at each retailer's website during January–September 2025 and January–September 2026 respectively. The DIY classification covers hardware and home improvement product pages, including flooring and wallpaper, identified via retail taxonomy. Each year's results are independently calibrated to the German adult population aged 18 and over. Reach reflects product-page browsing, not completed purchases. Retailers with changes smaller than approximately 1 percentage point fall within the margin of measurement variation.
These insights are based on the General Evidence Panel. Our data comes exclusively from users who are compensated for sharing their data. Become part of the panel & earn from your data